An HOA lien can appear on your property record without warning, and once it’s there, the consequences escalate quickly. In Santa Clara County, lien enforcement by homeowners associations follows strict legal procedures that can lead to foreclosure if left unaddressed.
At Pratt & Associates, we’ve seen homeowners lose properties over unpaid HOA dues that could have been resolved through negotiation or payment plans. Understanding how these liens work is your first line of defense against losing your home.
What Exactly Is an HOA Lien
An HOA lien is a legal claim against your property that the homeowners association records when you fall behind on assessments, fines, or related costs. In Santa Clara County, this lien attaches directly to the title of your home, creating what’s called a cloud on title. The moment a lien is recorded in county records, it becomes a public document that appears in title searches and can block refinancing or sales until resolved.
How Debt Grows Beyond Your Original Assessment
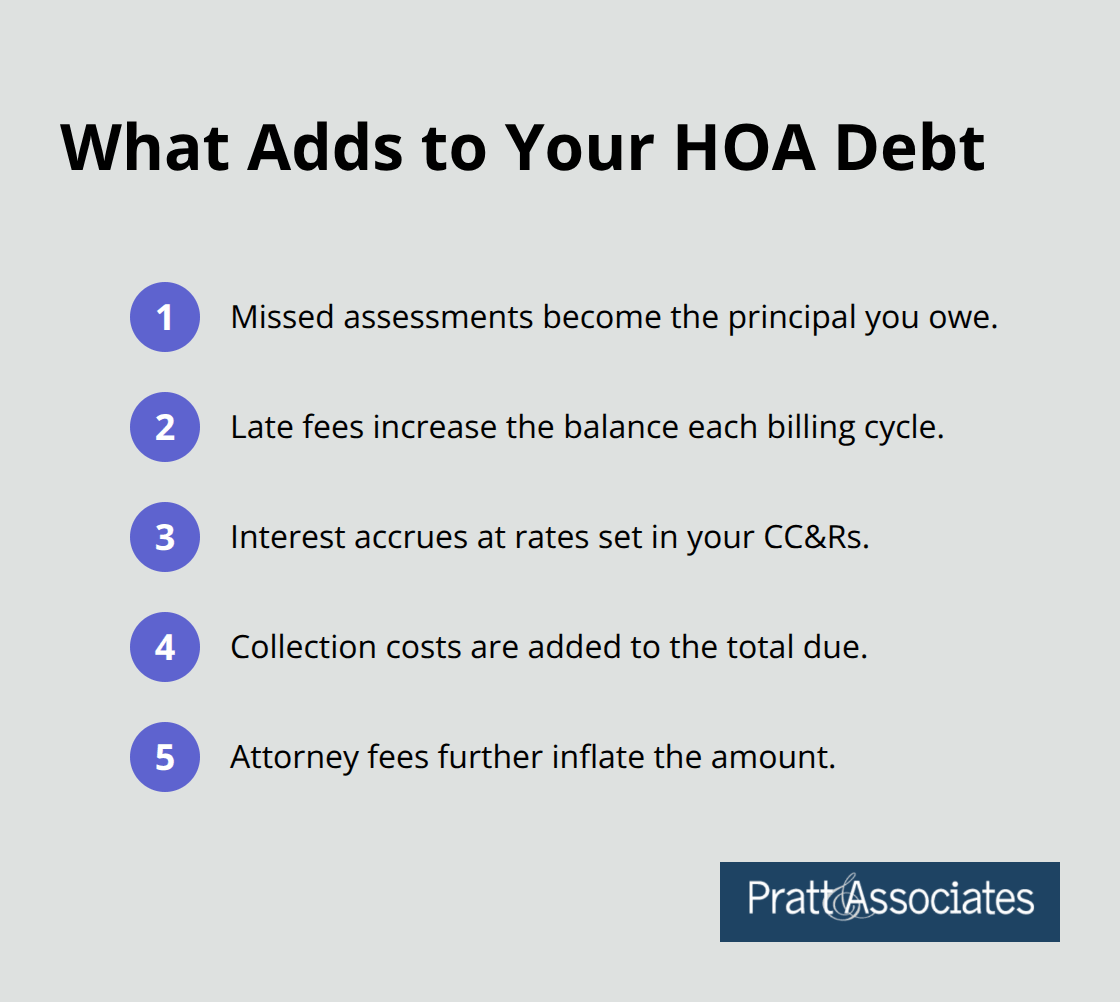
The amount owed isn’t just your missed payments. Late fees, interest accruing at rates specified in your CC&Rs, collection costs, and attorney fees pile on top of the original debt. Many homeowners are shocked to discover that a $2,000 unpaid assessment has grown to $4,500 or more within months due to these compounding charges.
California law under the Davis-Stirling Common Interest Development Act governs how and when HOAs can place liens on properties in Santa Clara County.
The Pre-Lien Notice: Your Critical Window
Before an HOA can record a lien, California law requires them to send you a written 30-day pre-lien notice detailing exactly what you owe and your right to dispute the charges. This notice must itemize every charge: principal assessments, late fees capped at the greater of $25 or 5% of the overdue amount, and any collection or legal costs. If you pay during this 30-day window, the lien never gets recorded. If you don’t, the HOA board must vote to approve the lien in an open meeting, and this decision gets documented in the board minutes. Only after this approval can the lien be formally recorded with the Santa Clara County Recorder’s Office.
The Foreclosure Threshold That Changes Everything
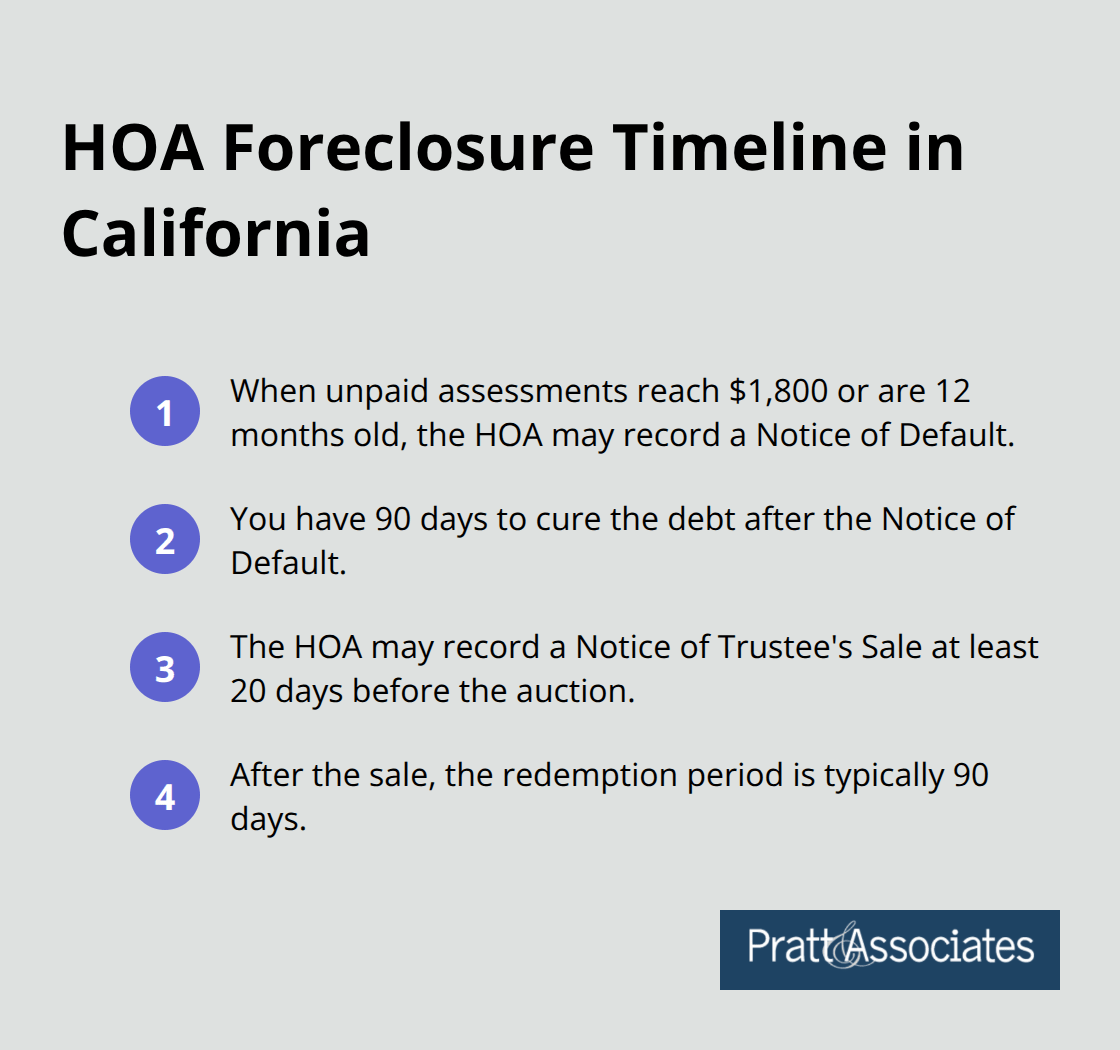
California’s Davis-Stirling Act sets a specific threshold before an HOA can foreclose on your home. The unpaid assessments must total at least $1,800 or the debt must be more than 12 months old. Fines and late fees alone don’t count toward this threshold, which means you could have significant penalties without triggering foreclosure. However, once you cross that $1,800 line, the HOA can proceed with what’s called a Notice of Default, giving you 90 days to cure the debt. If you don’t pay within those 90 days, the HOA can issue a Notice of Trustee’s Sale at least 20 days before the foreclosure auction. This timeline moves faster than a mortgage foreclosure, and unlike mortgage defaults, you typically get only a 90-day redemption period after the sale to reclaim your home.
Acting Fast During the Pre-Lien Period
The moment you receive a pre-lien notice, your window to act without a public record of debt closes rapidly. Contact the HOA or management company immediately to request an itemized statement of charges. Verify every line item, because errors do occur and can sometimes be challenged. If you dispute any charges, California law allows you to use the HOA’s internal dispute resolution process before a lien is recorded. Negotiating a structured payment plan with the HOA during this pre-lien period is far easier than dealing with a recorded lien that complicates everything from refinancing to selling. Many HOAs prefer collecting through payment plans rather than proceeding to foreclosure, so they’re often willing to negotiate if you approach them proactively before the 30 days expire. Understanding these financial consequences of a recorded lien-and how they affect your ability to sell or refinance-makes the next section essential reading.
How an HOA Lien Damages Your Financial Future
An HOA lien doesn’t sit quietly on your title. It actively damages your ability to sell, refinance, or borrow money against your home. The moment a lien is recorded in Santa Clara County, title companies flag it during any property search, and lenders immediately view your home as encumbered. If you plan to refinance at a lower interest rate, that lien will block the transaction until you pay it off. Buyers interested in your property will demand a significant price reduction or walk away entirely because they won’t accept a home with a cloud on title.
How Your Debt Multiplies
The payoff amount keeps growing-your original $2,000 debt accumulates compound interest, late fees capping at 5% of the overdue amount, and collection costs that can push the total to $5,000 or more. What started as a manageable assessment becomes a financial burden that compounds monthly. The longer you wait, the larger the gap between what you owe and what you can realistically pay.
Credit Damage and Borrowing Costs
Credit bureaus report these liens if the HOA files them as debts, which tanks your credit score and makes future borrowing expensive. A damaged credit profile affects not just home loans but also car financing, credit cards, and even job applications in some industries. The financial ripple effects extend far beyond your property.
The Foreclosure Timeline That Moves Fast
The foreclosure threat separates an HOA lien from ordinary debt. Once you cross that $1,800 threshold in unpaid assessments or stay delinquent for 12 months, the HOA can execute a Notice of Default followed by a Notice of Trustee’s Sale with only 20 days’ notice before the auction. Unlike mortgage foreclosures that take months to process through courts, HOA foreclosures in California move through nonjudicial sales quickly. You get a 90-day cure period after the Notice of Default, but if you don’t pay, the trustee’s sale happens, and you lose your home.
Why Speed Matters in HOA Foreclosure
The redemption period afterward is only 90 days in nonjudicial sales-far shorter than mortgage foreclosure redemption rights. The HOA doesn’t need to prove you’re a bad borrower or go through a judge; the Davis-Stirling Act gives them the power to take your property for unpaid assessments alone. This accelerated process means homeowners who wait too long to act find themselves with almost no time to respond. The window to negotiate closes faster than most people realize, and once the Notice of Trustee’s Sale is recorded, your options narrow dramatically. Understanding how to stop this process before it starts requires knowing exactly what steps you can take to resolve the debt.
Stop an HOA Lien Before It Destroys Your Financial Options
The moment you receive a pre-lien notice from your HOA in Santa Clara County, you face a critical choice. One path leads to a recorded lien that complicates refinancing and selling your home. The other path is action during the 30-day window before the lien appears on your title. Most homeowners underestimate their power during these 30 days, and that mistake costs them thousands of dollars.
Request and Verify Your Itemized Statement
Your first move is to request an itemized statement from the HOA or management company that breaks down every charge: principal assessments, late fees, interest, and collection costs. California law requires HOAs to provide this detail, and you have the right to examine it before the 30-day period expires. Verify each line item against your payment history and the CC&Rs. Late fees in Santa Clara County are capped at the greater of $25 or 5% of the overdue amount, so if your statement shows higher fees, that’s grounds for a dispute.
If you find errors or charges that don’t match your CC&Rs, file a dispute through the HOA’s internal process immediately. California law gives you the right to challenge improper charges before a lien is recorded, and many disputes are resolved without escalation.
Propose a Payment Plan During the Pre-Lien Period
Negotiating a payment plan during the pre-lien period is far more powerful than negotiating after a lien appears on your title. Contact the HOA management or board directly and propose a structured repayment arrangement. Most HOAs prefer collecting through payments rather than foreclosing because foreclosure is expensive, time-consuming, and generates bad publicity. Offer to pay a portion immediately and set up a realistic schedule for the remainder. Set up automatic payments or escrow arrangements to prevent future delinquencies. If you’re facing financial hardship, be transparent about it and propose a longer payment timeline. Many boards will work with homeowners who show they’re serious about resolving the debt.
Act Quickly Once a Lien Is Recorded
Once a lien is recorded, your leverage shrinks dramatically. Buyers and lenders will demand the lien be paid off before closing, and refinancing becomes nearly impossible until you satisfy it. If a lien has already been recorded on your property, contact a real estate attorney immediately. Some liens are invalid due to procedural errors, improper notice, or miscalculated amounts, and those can sometimes be challenged in court. The longer you wait after a lien is recorded, the more the debt grows through accruing interest and additional collection costs, making the problem exponentially worse. We at Pratt & Associates help homeowners evaluate whether charges are proper, whether the lien was recorded correctly under California law, and what remedies are available to protect your property rights.
Final Thoughts
An HOA lien in Santa Clara County can derail your financial plans faster than most homeowners expect. The 30-day pre-lien notice period is your most powerful window to act-during those 30 days, you can dispute charges, negotiate a payment plan, or resolve the debt before it appears on your title. Once a lien is recorded, your options narrow and the costs multiply through accruing interest and collection fees.
Staying current with your HOA payments prevents this situation entirely. Set up automatic payments through your bank or escrow account so missed payments don’t happen by accident, and review your CC&Rs and bylaws to understand exactly what assessments and fees you owe. Request the HOA’s financial statements and reserve studies regularly so unexpected charges don’t catch you off guard, and maintain proactive communication with your HOA management to prevent delinquencies from escalating into liens.
When lien enforcement becomes a real possibility, contact a real estate attorney immediately rather than waiting after a lien is recorded. We at Pratt & Associates help homeowners in Santa Clara County evaluate their options when facing HOA liens, negotiate with boards, and protect their property rights. The cost of legal guidance early in the process is far less than the cost of losing your home to foreclosure or paying inflated settlement amounts after a lien clouds your title.