Buying a home in Santa Clara County involves many moving parts, and one document often catches buyers off guard: the estoppel certificate. This form reveals what you actually owe to the HOA before you close on your property.
At Pratt & Associates, we’ve seen transactions derailed because buyers didn’t understand what estoppel certificates contain or how to obtain them quickly. Getting this document early prevents surprises at closing and protects your financial interests.
What an Estoppel Certificate Actually Reveals
An estoppel certificate is a formal statement from your HOA or property management company that lists exactly what you owe before closing. According to REALTOR.org, it confirms the property’s current financial status, including dues, assessments, fines, and liens. This isn’t a suggestion or estimate-it’s a binding document that protects you and creates legal obligations.
How Lenders Use Estoppel Certificates
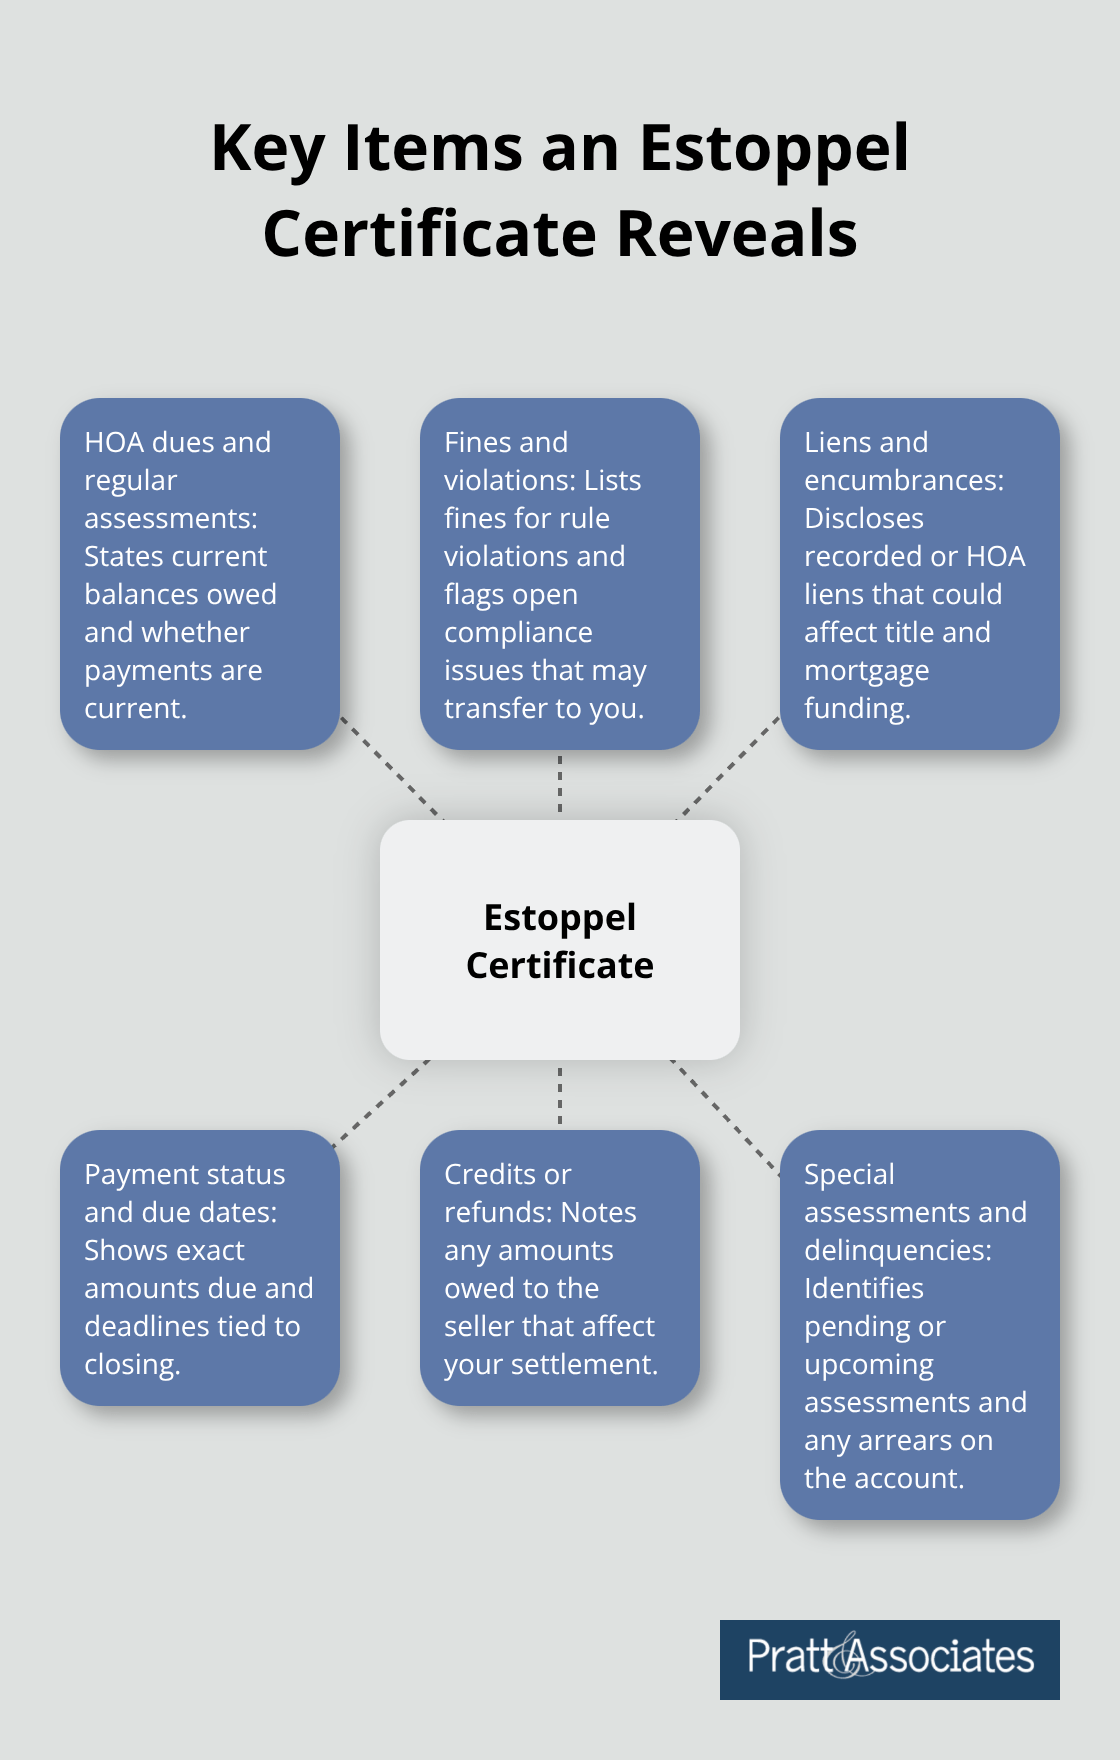
When you buy a home in Santa Clara County governed by an HOA, the lender demands this certificate before approving your mortgage. Without it, your closing stalls. The certificate typically shows the exact amount due, the due date, and whether any credits or refunds are owed to the seller, according to Nolo. It also flags delinquencies, pending or upcoming special assessments, and any liens that encumber the property.
Lenders require an estoppel because they need certainty about what obligations attach to the property after you take title. A lender won’t fund a mortgage if hidden HOA arrears could become your problem at closing. The certificate also protects you as the buyer-it prevents the seller from hiding unpaid assessments or violations that would transfer to you.
What the Certificate Costs and How Long It Takes
Florida law caps the estoppel fee at $299 per certificate if the owner’s account is current, though additional charges for rush processing or delinquent accounts can range from $100 to $200. The association or management company must issue the estoppel within 10 business days of a written request, or within 3 business days if you need a rush certificate.
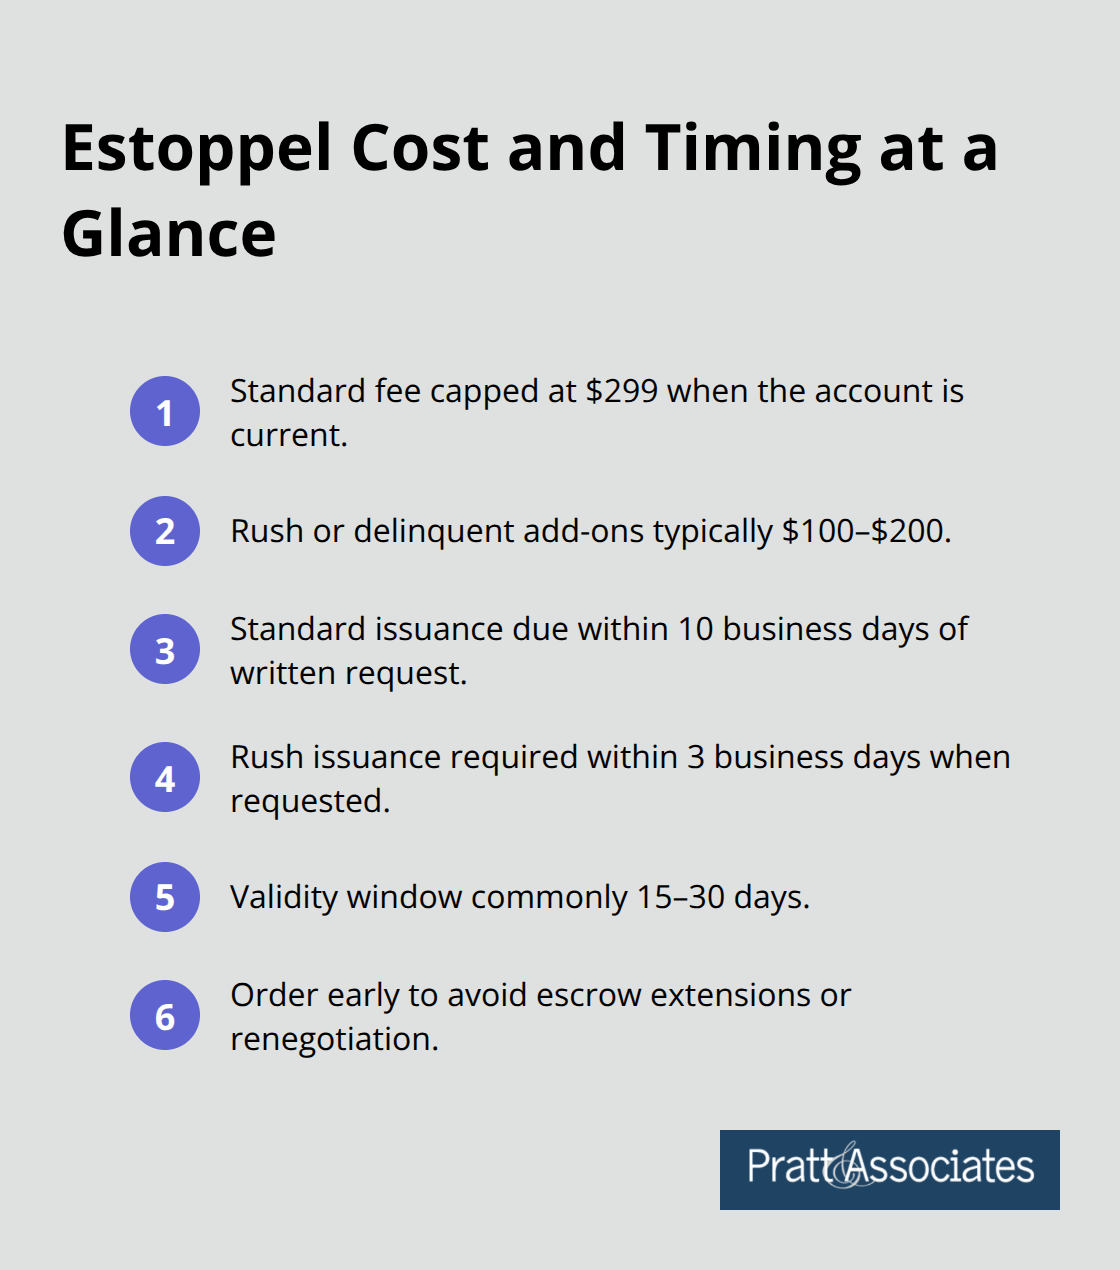
The estoppel is valid for a limited window, commonly 15 to 30 days, after which the numbers can change and a new certificate may be needed. Delays in receiving the estoppel can stall closing and may require extending escrow or renegotiating terms, so ordering it early is not optional-it’s essential.
When Estoppel Certificates Become Non-Negotiable
Any HOA-governed property in Santa Clara County requires an estoppel. Condominiums, planned communities, and properties subject to covenants, conditions, and restrictions all fall into this category. If the property has tenants or rental units, you’ll need an estoppel that confirms current rent, payment history, lease terms, and the lease end date, according to Nolo.
Investment properties with multiple units demand estoppel information for each unit to reduce post-closing disputes. Properties with pending HOA disputes or violations need estoppel certificates even more urgently because the certificate will disclose these issues before you commit to purchase. In some states, the estoppel also confirms there are no pending HOA lawsuits or judgments against the property.
How Estoppel Certificates Affect Your Negotiating Position
Nolo emphasizes that the certificate should flag any upcoming or projected special assessments to prevent surprise costs for you after purchase. If the estoppel reveals arrears, you and the seller typically negotiate credits at closing or require the seller to pay amounts before transfer. This negotiation happens because you have concrete numbers on paper, not vague promises.
The certificate becomes part of your closing package and affects title clearance and the title company’s risk assessment. Clear, accurate reporting simplifies the closing process and prevents last-minute complications. Understanding what the estoppel contains before you receive it helps you prepare for these negotiations and protects your financial interests.
Once you understand what an estoppel certificate reveals, the next step is recognizing the specific information it contains and how that information shapes your purchase decision.
What the Estoppel Certificate Actually Lists
The estoppel certificate sits on your closing table with one job: to tell you exactly what financial and legal obligations transfer with the property. When you review it, you’re looking at real numbers tied to your purchase decision, not guesses or estimates.
Financial Obligations and Assessments
The certificate itemizes outstanding HOA dues, any unpaid special assessments, fines for rule violations, and liens placed against the property by the association. According to REALTOR.org, it also reveals pending or upcoming special assessments that could hit you months after closing. Special assessments range from a few hundred dollars to tens of thousands depending on the community’s reserve fund status and planned improvements. You need to see these numbers before you commit to purchase because they affect your actual cost of ownership.
Lease Terms and Tenant Information
The certificate goes deeper than just dollars owed. It discloses lease terms and rental obligations if the property includes tenant units, confirming current rent, payment history, and lease expiration dates according to Nolo. This information protects you from inheriting tenant disputes or discovering that a lease expires sooner than you expected. Investment properties with multiple units require estoppel information for each unit to reduce post-closing disputes.
Violations, Liens, and Legal Encumbrances
The estoppel flags open violations of HOA rules that could become your liability after closing. In some states, it confirms whether pending HOA lawsuits or judgments encumber the property. The certificate also shows whether liens exist against the title, which your lender will use to assess risk before funding your mortgage. If arrears exist, you and the seller negotiate credits at closing or require the seller to cure the debt before transfer, as noted by Nolo.
The Time-Sensitive Nature of Estoppel Information
The certificate is typically valid only 15 to 30 days, so the numbers you see represent a snapshot in time, not a promise about future assessments or changes in HOA fee structures. This time limit means ordering the estoppel early prevents closing delays and gives you room to negotiate if the certificate reveals unexpected obligations. The moment you receive the estoppel, you should cross-check it against the actual HOA documents and lease agreements to catch any inconsistencies before they become closing problems.
Common Issues That Delay Estoppel Certificates in Santa Clara County
HOAs Miss Deadlines and Force Closing Delays
The 10-business-day deadline for estoppel certificates sounds reasonable until you’re the buyer waiting for it. HOAs and property management companies in Santa Clara County routinely miss this window, and when they do, your closing date slips. According to REALTOR.org, delays in receiving the estoppel can stall closing and may require extending escrow or renegotiating terms. Management companies take three weeks or longer to produce a certificate, forcing buyers to choose between losing their closing date or accepting incomplete information. The problem intensifies when you need a rush certificate within three business days-some management companies lack the staffing to comply. Your lender won’t fund the mortgage without the estoppel, and your seller won’t wait indefinitely.
How to Prevent Management Company Delays
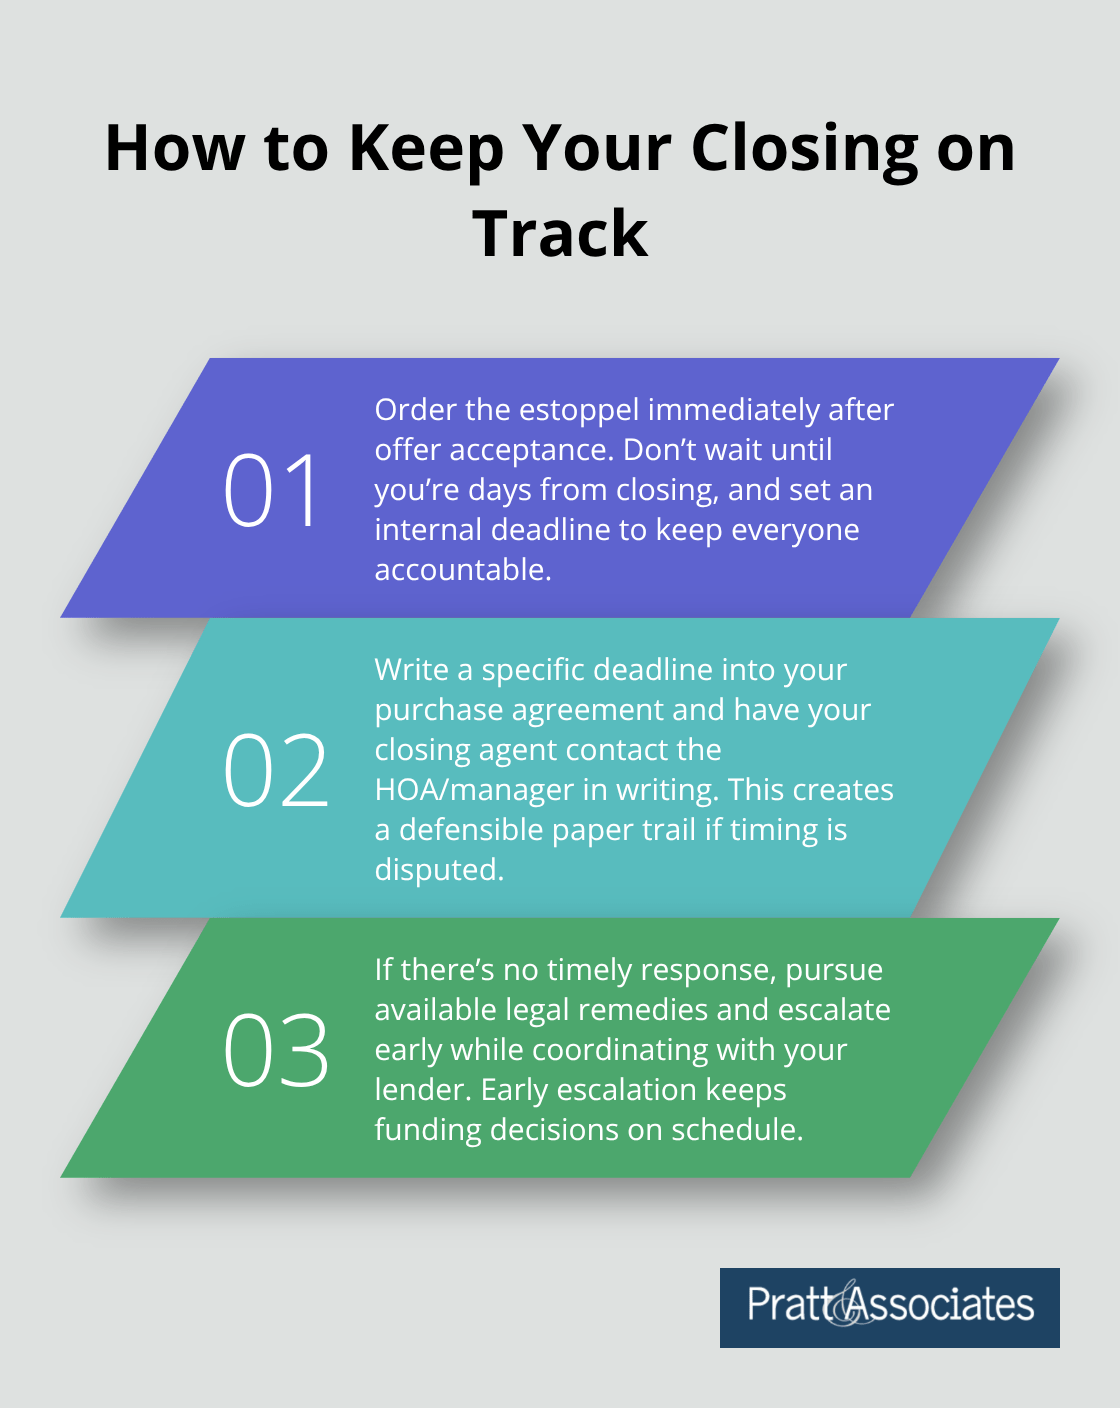
Order the estoppel the moment your offer is accepted, not when you’re 10 days from closing. Include a specific deadline in your purchase agreement tied to your closing date, and have your closing agent contact the management company in writing immediately. If the HOA or management company fails to respond within the required timeframe, Florida law provides remedies to compel delivery, though pursuing them takes time you don’t have during a closing. Written communication creates a paper trail that protects you if disputes arise about when the request was made.
Discrepancies Between Documents Create Last-Minute Problems
Inconsistencies between the estoppel and your actual lease or HOA documents create another category of problems that derail transactions at the final hour. The certificate might state your HOA dues are current when the HOA records show a $2,000 arrear, or it might list a special assessment that contradicts what’s in the CC&Rs. Nolo emphasizes that you should cross-check the estoppel carefully for accuracy, and disputes should be raised promptly with the HOA or management company. These inconsistencies force renegotiations when both parties thought they had closed the deal, and lenders frequently require their own estoppel certificate, which can complicate funding decisions if discrepancies exist.
Verify Information Before Closing Day
The title company’s risk assessment depends on the accuracy of the estoppel, and they’ll hold up the closing if they spot conflicting information. Your closing timeline compresses dramatically when you discover these errors late. Coordinate with your lender, HOA, and closing agent early in the transaction to verify estoppel information against the actual governing documents before you reach closing day. If you find discrepancies, address them in writing and get written confirmation from the management company that corrections have been made. Legal counsel can review the estoppel against the HOA documents before closing and protect your interests against last-minute surprises that could cost you thousands or kill the deal entirely.
Final Thoughts
Estoppel certificates form the foundation of a protected real estate transaction in Santa Clara County, and ordering them early prevents the delays and disputes that derail closings. Request the certificate the moment your offer is accepted, include a specific deadline in your purchase agreement, and have your closing agent submit the request in writing to create documentation. Coordinate with your lender to confirm they’ve received the certificate and flagged any concerns before closing day arrives.
Cross-check the estoppel against your lease, CC&Rs, and HOA governing documents to catch inconsistencies early (and contact the management company in writing if you find errors). Working with legal counsel transforms the estoppel from a confusing document into a strategic tool that protects your financial interests. An attorney reviews the certificate against your actual obligations, identifies hidden risks like pending special assessments or unresolved violations, and negotiates credits or cure periods with the seller when problems surface.
At Pratt & Associates in Los Gatos, we handle the real estate transactions where estoppel certificates matter most. We review these documents before they become closing problems and protect your interests when discrepancies emerge. Contact Pratt & Associates to ensure your HOA transaction closes smoothly and your financial interests remain protected from start to finish.