Buying a home in Santa Clara County means navigating HOA disclosures-documents that reveal everything from financial health to pending lawsuits. These disclosures aren’t optional paperwork; they’re your window into whether an HOA is well-managed or heading toward trouble.
At Pratt & Associates, we’ve seen buyers skip this step and regret it later. The right information now prevents costly surprises after closing.
What Sellers Must Disclose and Why It Matters
California law requires sellers to hand over a comprehensive disclosure packet before you remove your contingencies, and in Santa Clara County, this obligation is mandatory under Civil Code 4525. The packet must include CC&Rs, articles of incorporation, bylaws, operating rules, the annual budget report, and the most recent reserve study summary. Sellers also must disclose current HOA dues, any pending assessments, enforcement actions, violations, and litigation involving the association. If they omit items or provide outdated documents, you have legal recourse. The seller bears responsibility for completeness, and incomplete packets create liability under both the Davis-Stirling Act and the Transfer Disclosure Statement. This means you can demand missing documents, and if the seller refuses or delays beyond ten days, California law allows you to claim statutory damages under Civil Code 4540. Don’t accept vague answers or promises to send documents later-obtain everything before closing. Recent changes under SB 410 now require the most recent SB 326 inspection report (for balconies and elevated elements) to be included in the disclosure packet starting January 1, 2026, so verify the property’s inspection status early.
What Documents Actually Arrive in Your Packet
Financial statements show the HOA’s income, expenses, and reserve fund balance, while a reserve study projects major repairs over the next 20 to 30 years and estimates funding needs. The packet includes meeting minutes from the past 12 months, which reveal how the board operates and what issues they’ve addressed. You’ll receive a current insurance summary under Civil Code 5300, detailing what the master policy covers and what gaps exist. Governing documents spell out your restrictions-everything from paint colors to parking rules to pet limits. The disclosure must also itemize regular and special assessments, unpaid amounts, fines, late charges, and collection costs. Litigation notices are critical; if the HOA faces a lawsuit or construction defect claims, you need to know about it.
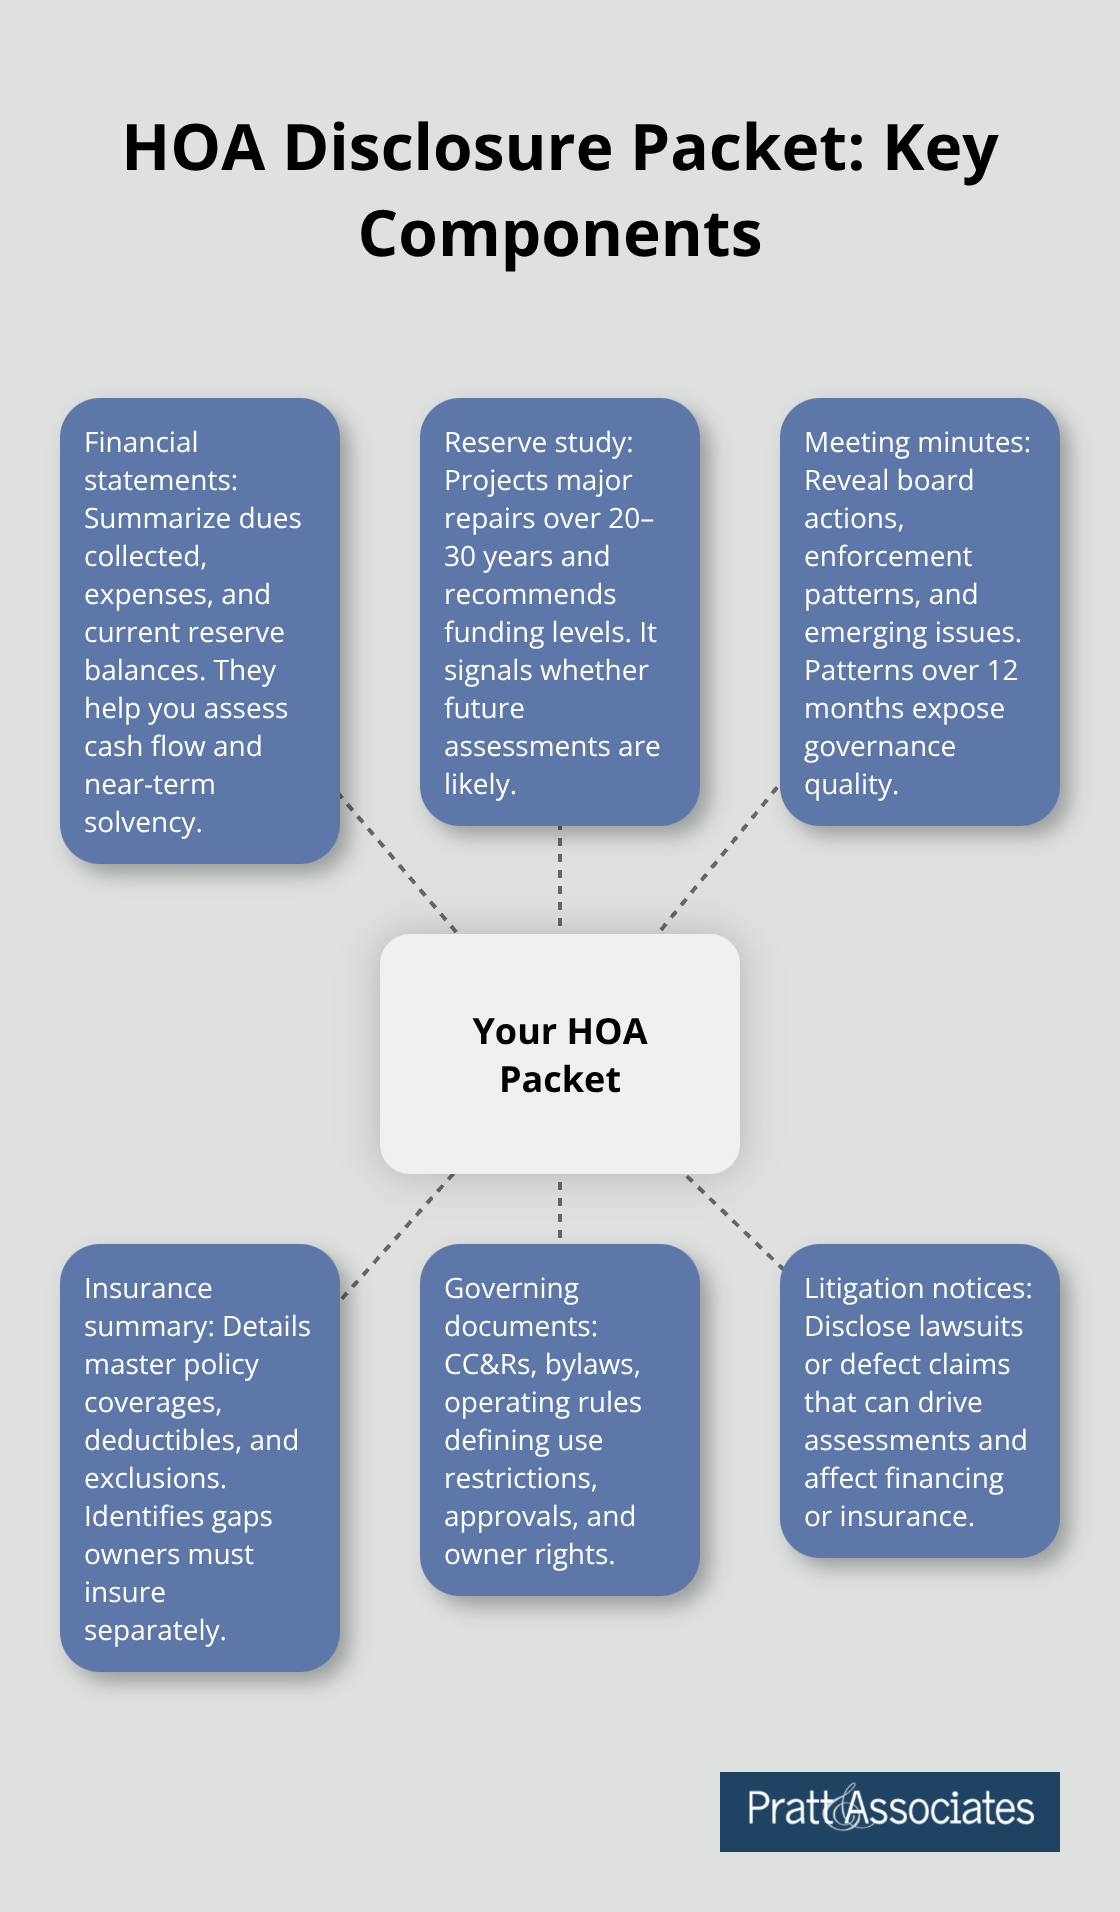
Many buyers overlook meeting minutes, but they’re invaluable-they show enforcement patterns, board disputes, and whether the HOA operates transparently or dysfunction exists. Request these documents immediately after your offer is accepted, not days before closing, so you have time to review them thoroughly with an attorney if needed.
Why These Disclosures Protect You
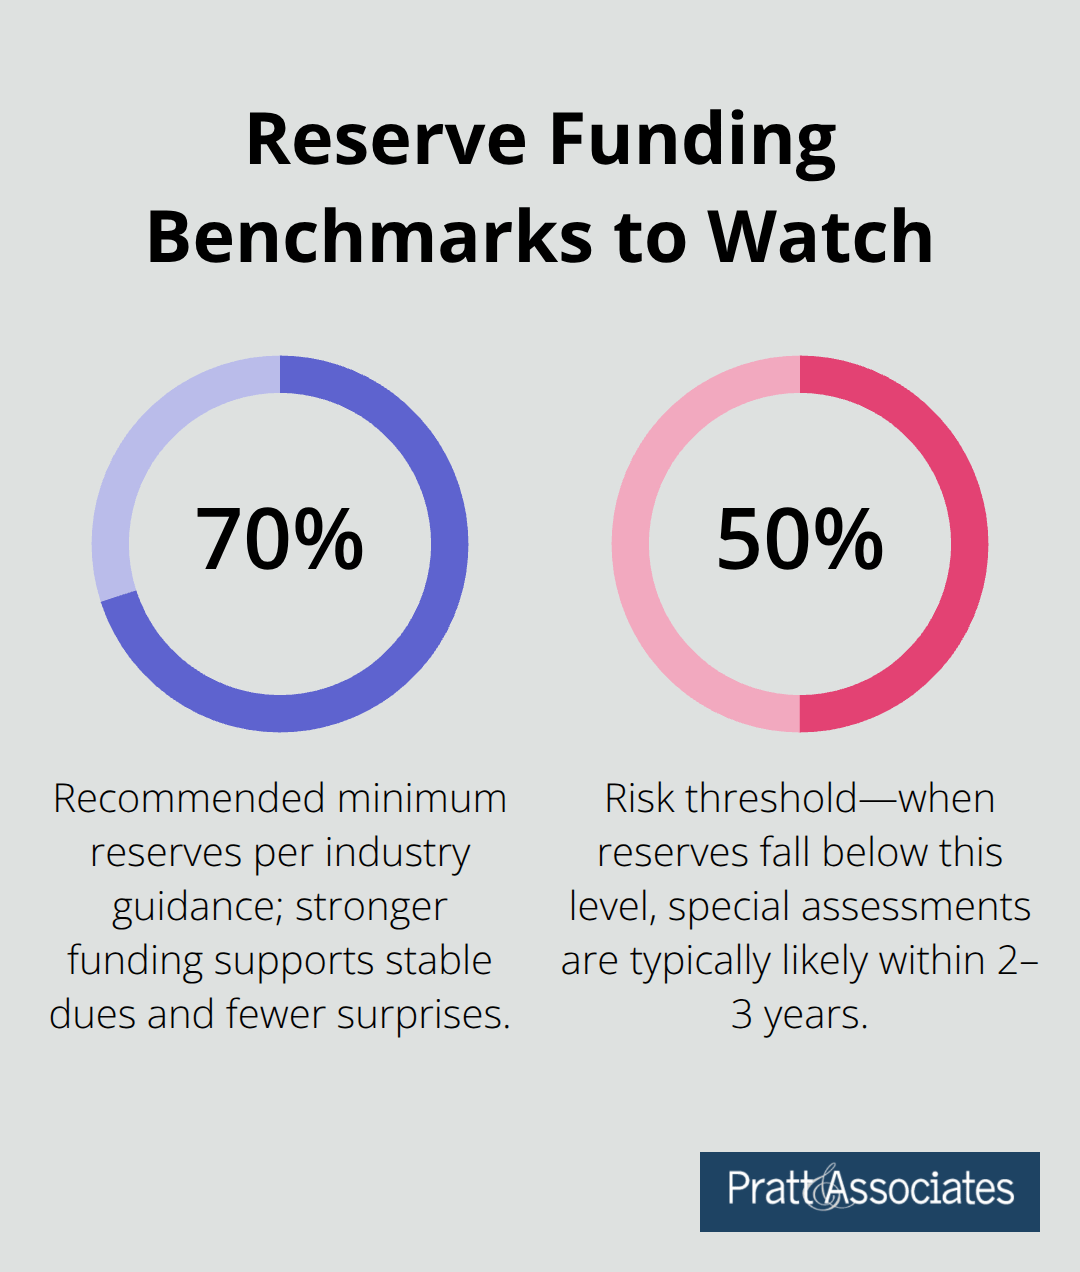
Undisclosed HOA problems can crater property values and block financing after closing. Lenders like Fannie Mae and Freddie Mac won’t fund a property if critical disclosures are missing or SB 326 compliance status remains unresolved, leaving you unable to refinance or sell. If litigation is hidden and emerges later, you may face sudden special assessments to cover legal costs or settlements. Low reserves mean future dues hikes are inevitable-the National Association of Realtors advises checking whether reserves reach 70 percent or higher of what a study recommends.
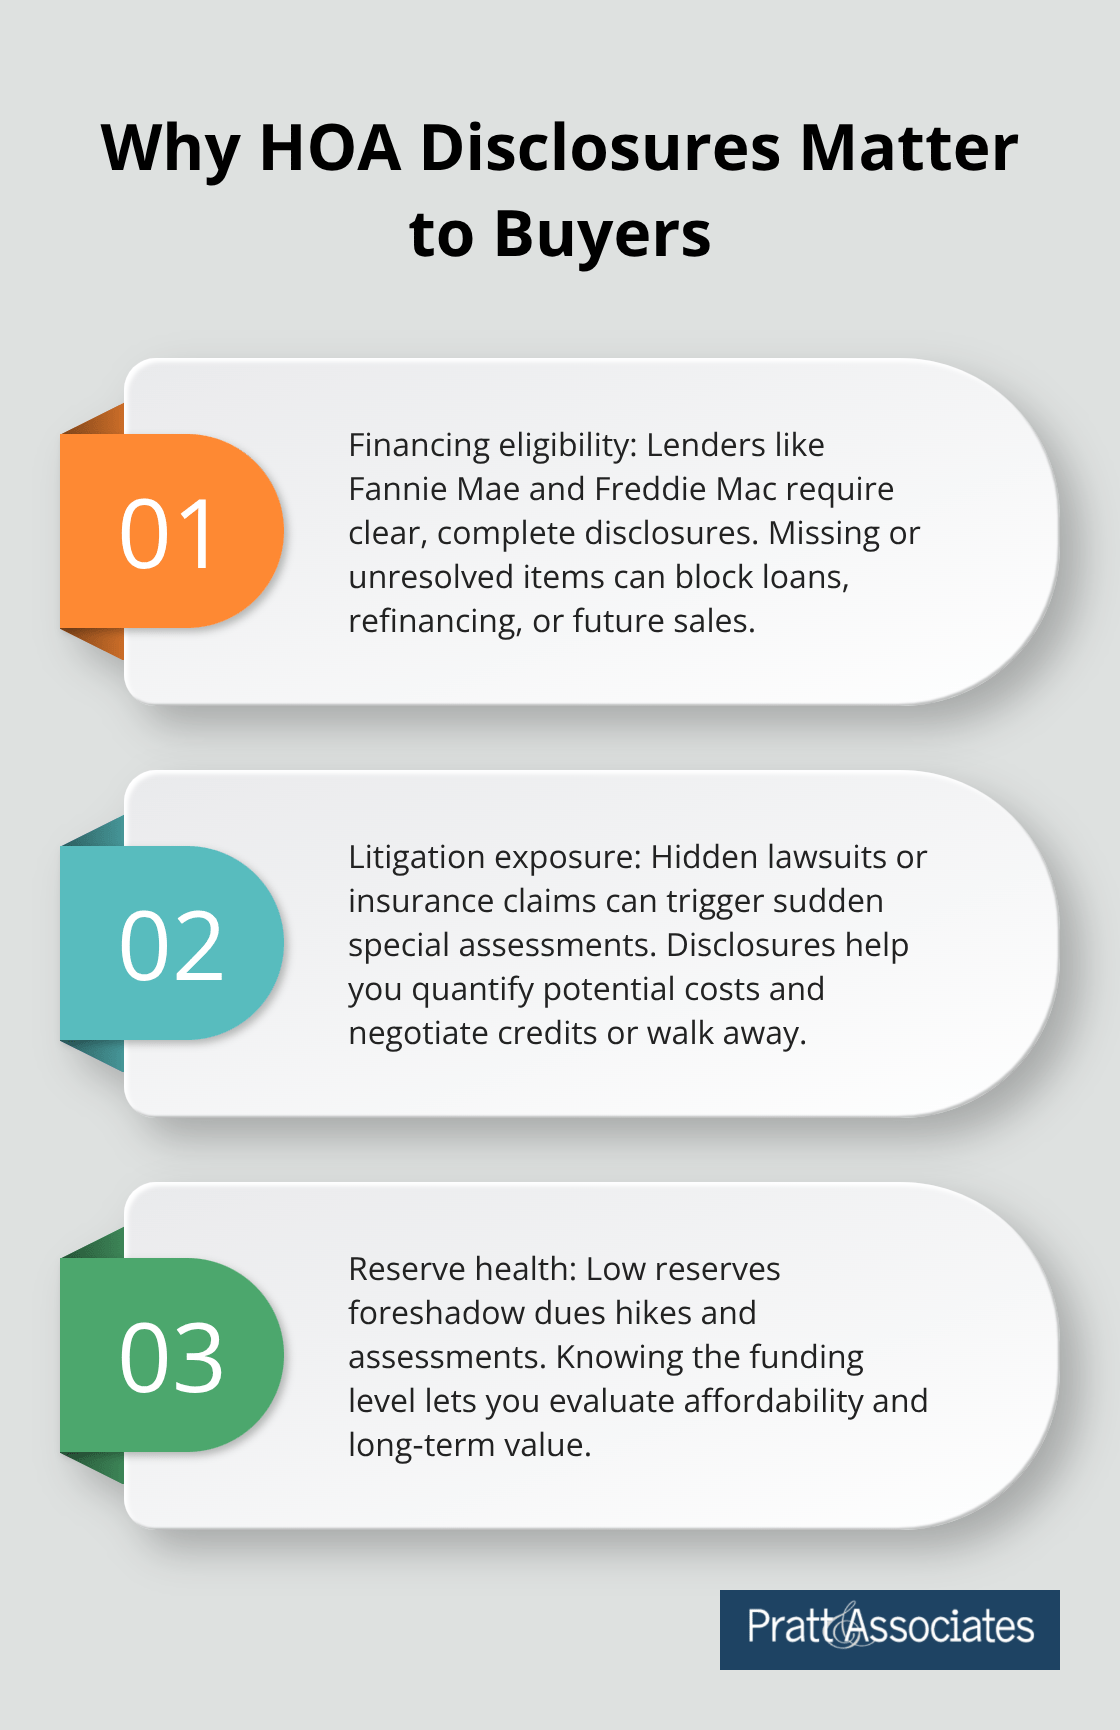
Underfunded reserves correlate with higher future assessments and signal declining property values. Enforcement violations in the minutes reveal whether the HOA targets certain owners unfairly or ignores violations inconsistently, both of which affect your rights and resale prospects. Disclosures also show whether rental restrictions exist, which impacts your ability to lease out the property and affects mortgage eligibility under FHA guidelines. If the seller fails to disclose material facts and you discover fraud after closing, California law allows rescission under Civil Code 1689 and fraud claims under Civil Code 1709 with a three-year statute of limitations. Reviewing disclosures before removing contingencies is non-negotiable-it’s your only leverage point to renegotiate terms, request seller credits, or walk away without penalty.
Moving Forward: What Comes Next
The documents you receive paint a picture of the HOA’s financial health, governance practices, and potential liabilities. Understanding what red flags to spot in these materials determines whether you proceed with confidence or uncover problems that demand further investigation.
Key Documents You’ll Find in HOA Disclosure Packages
Financial statements show exactly what the HOA collected in dues, how much it spent, and what sits in reserves. The National Association of Realtors recommends checking whether reserves equal at least 70 percent of what the reserve study says you need. If reserves fall below 50 percent, special assessments will likely arrive within two to three years.
The reserve study projects major repairs over 20 to 30 years and estimates costs for roof replacements, foundation work, exterior painting, and elevator maintenance. A stale reserve study (more than three years old) signals that the HOA isn’t planning ahead, which means surprise bills are coming. Look at the study’s funding plan: does it recommend monthly contributions, lump-sum payments, or phased increases? If the HOA ignores the study’s recommendations, reserves will continue deteriorating. Independent firms conduct more credible reserve studies than in-house assessments, and lenders weight independent studies more heavily when evaluating financing eligibility.
The current insurance summary under Civil Code 5300 details what the master policy covers and what deductible applies. Most HOA policies cover common areas and shared structures but exclude individual unit interiors, meaning you’ll need separate homeowners insurance for your interior walls, fixtures, and personal property. The summary shows whether the HOA carries adequate liability coverage and whether the policy has exclusions that could leave owners exposed. If the building has elevated elements like balconies, the SB 326 inspection report (required in the disclosure packet starting January 1, 2026) reveals safety findings and any deferred maintenance issues that could affect insurance premiums or financing approval.
Governing Documents Spell Out Your Real Restrictions
The CC&Rs and bylaws contain the HOA’s actual rules. Most buyers skim these and miss critical details that directly affect property use and resale value. The CC&Rs cover architectural controls, parking restrictions, pet policies, rental limits, and use prohibitions. In Santa Clara County, architectural review committees typically require 30 to 60 days to approve exterior changes, and many communities restrict paint colors to pre-approved palettes.
If you plan to install solar panels, the CC&Rs may allow them but restrict placement or require board approval, which takes time and may delay your project. Pet policies often cap pets at two or three per household and may require DNA testing for waste compliance in common areas. Rental restrictions are especially important: some HOAs prohibit short-term rentals entirely, require minimum lease terms of one year, or cap the number of units that can be rented. These restrictions directly affect your ability to lease the property and may make the home ineligible for FHA financing under Fannie Mae guidelines.
The bylaws detail how the board operates, how many members serve, and how decisions are made. Look for transparency provisions: can owners attend all meetings, or are some closed? Do owners have access to financial records and meeting minutes? If the bylaws limit owner access or allow the board to operate in secret, governance problems often follow.
Meeting Minutes Reveal Enforcement Patterns and Board Dysfunction
Meeting minutes from the past 12 months show what the board actually does versus what the bylaws say it should do. Enforcement patterns matter: if the minutes show the HOA aggressively fining owners for minor landscaping violations but ignoring a neighbor’s illegal renovation, the HOA enforces rules inconsistently, which affects your rights and your resale prospects. Look for recurring disputes between the board and owners, patterns of fines or liens, and how violations are resolved.
If the same owner appears in minutes repeatedly, either that owner is flagrantly non-compliant or the HOA targets them unfairly. Minutes also reveal board conflicts: if directors argue constantly about finances or governance, management instability may affect decision-making quality. Check whether the board discusses reserve funding, upcoming special assessments, or capital projects. If reserves are low but the board hasn’t discussed funding plans, financial trouble is brewing.
Minutes from the past year should show whether the HOA addressed pending litigation, construction defect claims, or insurance claims. If litigation is mentioned but no updates appear for months, the HOA may be hiding progress or facing difficult negotiations. Request these minutes well before closing so you have time to identify patterns and consult an attorney if red flags appear. The patterns you uncover in these records will guide your next steps in evaluating whether this property and HOA align with your long-term ownership goals.
Common Red Flags in HOA Disclosures
Underfunded Reserves Signal Future Special Assessments
Underfunded reserves represent the most dangerous red flag in any HOA disclosure. The National Association of Realtors recommends that reserves reach at least 70 percent of what the reserve study recommends, but many Santa Clara County HOAs hover between 30 and 50 percent. When reserves fall below 50 percent, special assessments typically arrive within two to three years. A special assessment means the HOA will bill you thousands of dollars on top of your monthly dues to cover major repairs the association deferred.
If the reserve study recommends 5 million dollars in funding but the HOA has only 2 million set aside, owners will absorb that 3-million-dollar gap through special assessments. Ask the seller directly whether any special assessments are planned or discussed in board meetings. Check the meeting minutes for conversations about capital repairs like roof replacements, foundation work, or exterior painting. If the minutes show the board acknowledging needed repairs but the reserve study is three or more years old, the HOA operates without current information, and your future costs remain unpredictable. Lenders view underfunded reserves as a financing risk, which can narrow your refinancing options down the road.
Litigation and Legal Claims Create Hidden Costs
Litigation and pending legal issues represent the second major red flag. If the disclosure reveals the HOA faces a lawsuit, construction defect claim, or insurance claim, you need specifics, not vague statements. Review the meeting minutes to see what the board has said about litigation timelines, settlement discussions, and potential costs. A case that drags on for years signals either complex problems or board dysfunction. Construction defect claims are particularly serious in Santa Clara County because they can trigger mandatory SB 326 inspections of elevated elements like balconies, and if defects are found, remediation costs can spike insurance premiums or render the property temporarily unfinanceable. Ask your lender whether pending litigation affects financing approval, because some lenders will not fund properties with active HOA lawsuits.
Inconsistent Enforcement Exposes You to Arbitrary Fines
Inconsistent enforcement of rules is subtler but equally damaging. Examine the meeting minutes for enforcement actions: fines issued, violations cited, and resolutions reached. If the board fined one owner 500 dollars for a landscaping violation but ignored a neighbor’s illegal deck renovation, the HOA enforces rules selectively. This means enforcement decisions depend on board preferences rather than written rules. Selective enforcement exposes you to arbitrary fines and creates liability if you later challenge the HOA’s decision. It also signals that the board prioritizes personal relationships over governing document compliance, a governance weakness that affects long-term property values and owner disputes. When you spot these patterns in disclosures, consult an HOA attorney in Santa Clara County before removing your contingencies, because these issues directly impact your financial exposure and resale prospects.
Final Thoughts
Request all documents immediately after your offer is accepted, not days before closing. Read the financial statements first to understand reserve funding levels and whether special assessments loom, then cross-reference the reserve study with meeting minutes to confirm the board acknowledges upcoming capital repairs. Scan the CC&Rs for restrictions that affect your intended use-solar installations, rental plans, pet ownership, or exterior modifications-and pay close attention to enforcement patterns in the meeting minutes.
An HOA attorney in Santa Clara County reviews your specific disclosure packet and flags issues that standard buyer checklists miss. They identify whether pending litigation poses genuine financial risk, whether reserve funding aligns with realistic repair timelines, and whether enforcement patterns expose you to arbitrary fines. They also confirm that the disclosure packet complies with Civil Code 4525 requirements and that nothing material has been omitted.
We at Pratt & Associates help buyers navigate HOA disclosures for buyers and understand their legal implications before closing. Our attorneys review governing documents, financial records, and litigation history to identify risks you might otherwise overlook, and we work with you to negotiate seller credits for anticipated HOA costs or to structure contingencies that protect your interests. Contact Pratt & Associates to discuss your specific situation and ensure your purchase decision rests on complete, accurate information.